

Split Pay: Split Bills in Two

- 467.00 Reviews
- 4.8
- Downloads
- 100,000+
Our take on Split Pay: Split Bills in Two from Appgk
Managing a large payment is stressful enough without having to ask someone else to cover the whole amount first. That is the problem Split Pay tries to address: it is a free finance app from Split Pay designed around dividing rent, mortgage, and car payments into smaller parts. I found the idea immediately practical, especially for people whose income arrives on a different rhythm from their biggest monthly bills. At the same time, its usefulness depends on how comfortable you are handling a payment workflow through an app rather than using a bank’s built-in tools.
The app is available to an Everyone audience, runs on operating system version 10 or later, and has reached more than 100,000 installs. Its current version is 2.0.4, while the overall response from users is strong: a 4.8 average from roughly 3,000 ratings, alongside hundreds of written reviews. Those figures suggest that the central idea is landing well with many people, but they do not remove the need to think about whether the experience suits your own financial routine.
How clearly the app explains a split-payment routine
My first impression is that the product has a focused purpose rather than trying to become a complete banking dashboard. The store summary points directly to rent, mortgage, and car payments, and that focus is useful. Instead of making me sort through budgeting categories, investment tools, or unrelated money features, the concept stays close to one recurring problem: turning a major obligation into more manageable payment moments.
That narrow scope can make navigation easier for someone who is not interested in learning a complicated finance platform. A person opening it for the first time is likely thinking about one question: how can I handle this large bill without letting the due date overwhelm the rest of the month? The app’s identity answers that question quickly. I also appreciate that the developer name, Split Pay, matches the function closely, so there is little ambiguity about what kind of tool I am considering.
Best Parts of Split Pay: Split Bills in Two
Things to Keep in Mind About Split Pay: Split Bills in Two
For readability, the strongest advantage is the limited subject matter. A focused payment app has less reason to bury the main task under dense charts or a long list of account types. That matters to me because financial screens can become tiring when every number competes for attention. A cleaner route from opening the app to understanding the next payment can help users who prefer plain, task-based interfaces.
There is an important distinction, however, between a simple concept and a fully simple experience. Splitting a payment involves dates, amounts, account timing, and personal responsibility. Even if the screen itself is easy to read, I still need to understand exactly what each action means before relying on it for a housing or vehicle obligation. My advice is to move slowly during the first setup, read each confirmation, and compare the planned amount with the original bill rather than assuming that “split” automatically means “set and forget.”
News and Features Related to Split Pay: Split Bills in Two

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A useful way to approach the app is to treat it as a payment-planning aid first. Before entering anything, I would write down the full bill, its due date, and the days when money normally reaches my account. That small preparation makes the app easier to use because I am not trying to solve the arithmetic and learn the interface at the same time. It also gives me a reference point if the proposed schedule feels different from what I expected.
What the focused design means for different users
Someone who already uses a detailed budgeting service may find this narrower approach refreshing. A full budgeting app often asks users to connect accounts, categorize purchases, monitor spending, and maintain a larger financial picture. Split Pay is more appealing when the immediate problem is one recurring large payment rather than overall financial analysis. In that situation, fewer distractions can be a form of accessibility: the user has less information to filter before reaching the relevant task.
Don't want to read the full review?
On the other hand, a person who wants automatic account forecasting, shared household budgeting, debt tracking, or extensive reports may feel that the app does not replace a broader financial system. I would not choose it as my only money-management tool if I needed a complete view of cash flow. Its value is more specific. It helps frame a large payment in smaller pieces, while a conventional budgeting app helps explain where all of my money goes.
This difference is especially important for users with limited financial confidence. A focused tool may feel less intimidating, but it can also make the surrounding context less visible. I would use it alongside a simple written budget or calendar, particularly when the payment is essential. That combination preserves the app’s straightforward purpose without asking it to serve as a complete financial record.
Screenshots
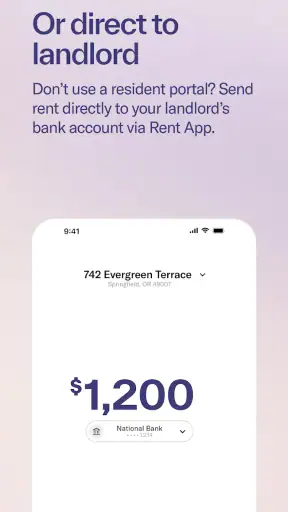
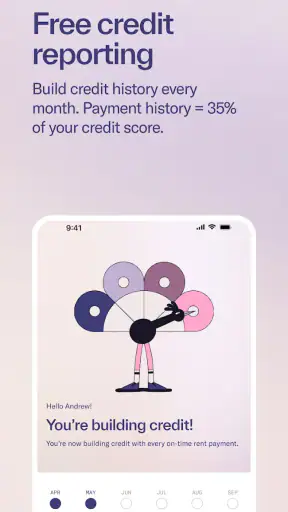
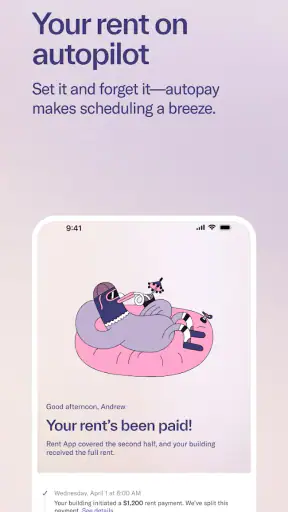
Using it with different abilities, routines, and environments
Readability is more than large text
When I think about inclusive use, I look beyond whether words appear on a screen. Financial information needs clear hierarchy: the amount, timing, and next action should not be confused with explanatory text. Split Pay’s single-purpose structure gives it a good starting point because users are not expected to navigate a large collection of unrelated services. That can benefit people who experience cognitive fatigue, attention difficulties, or anxiety around money.
I would still recommend checking the display at the beginning of setup rather than assuming that every important detail will be equally prominent on every phone. Users with low vision may need to enlarge system text or use screen magnification, and that can sometimes change how much information fits at once. If a confirmation becomes crowded after text enlargement, the safest response is to review one screen at a time and avoid rushing through a payment decision.
Plain language also matters. The idea of paying a large obligation in portions is easy to understand in everyday terms, but financial actions can become confusing when labels are abbreviated or when a schedule is shown without enough context. I found that the best way to reduce uncertainty is to connect every in-app figure to a real-world note: “this is part of my rent,” “this is the amount I expect after payday,” or “this is the remaining portion before the bill is due.” That habit is useful for anyone, and particularly for people who find abstract numbers difficult to process.
Users who rely on spoken feedback should pay attention to the order in which information is announced by their device. A finance app is easier to use with assistive technology when the amount and action are encountered in a logical sequence, but I would not make a critical payment based on audio alone without reviewing the final result through a second method. Reading the confirmation aloud, checking it visually when possible, or asking a trusted person to verify the details can prevent an avoidable mistake.
Motor, sensory, and attention considerations
Payment tasks can be difficult for people with limited dexterity, tremors, or fatigue because they combine precise taps with consequences that may be hard to reverse. My practical recommendation is to use the app when you have time and a stable surface, not while walking, commuting, or trying to manage several things at once. A focused finance tool is most helpful when the user can pause between entering information and confirming it.
For people sensitive to visual clutter, the app’s subject-specific purpose may be less tiring than a full banking application filled with promotional panels and unrelated account activity. For users who are easily distracted, the same focus can make it easier to stay with one task. I would keep notifications and other interruptions to a minimum during setup, then save a separate reminder in my calendar so I do not depend on memory alone.
Motor accessibility also includes the consequences of accidental taps. I would avoid repeatedly tapping a button simply because a screen seems slow to respond, especially when dealing with a payment action. Waiting for the screen to update and checking for a visible change is safer than creating duplicate activity through impatience. This is not a criticism unique to Split Pay; it is a sensible habit for any financial app, but the stakes are higher when the payment concerns housing or a vehicle.
People with hearing loss should not be expected to rely on sound cues to understand a financial result. The important outcome should be confirmed in text or another visible form. Likewise, users with light sensitivity may prefer a lower-glare environment on the phone itself. I cannot treat those device settings as features of the app, but they can make a focused payment workflow more comfortable and reduce the chance of abandoning the task because the screen is tiring.
Situational access: when splitting a bill genuinely helps
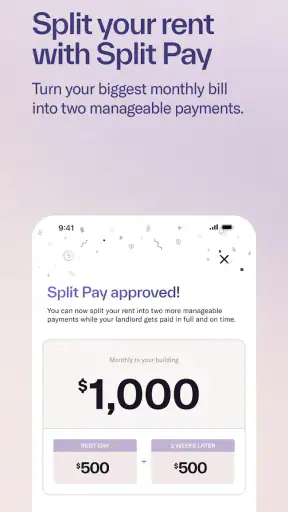
The clearest everyday scenario is a renter paid weekly or irregularly. Imagine that the full rent is due at the start of the month, while income arrives in several smaller deposits. Without a splitting tool, that person may need to hold the entire amount in a separate account, ask a friend or partner to cover the difference temporarily, or rely on a credit card. Split Pay is attractive because it is built around matching a large recurring obligation to a less convenient income pattern.
There is a similar use case for a car payment. Someone may receive money at different points in the month and prefer to reserve portions gradually instead of watching the entire payment leave at once. The benefit is not that the obligation disappears; it is that the user can organize the path toward it in a way that better reflects real cash flow. That distinction is important. I see the app as a planning and payment convenience, not a way to make an unaffordable bill affordable.
Mortgage payments introduce a higher level of caution. A homeowner may appreciate the ability to divide the financial effort, but the consequences of misunderstanding a schedule are more serious than with an informal household expense. I would use the app only after confirming how the resulting payments align with the lender’s requirements and the actual due date. If a lender requires one specific transaction or imposes conditions around partial payments, a bank or lender-approved method may be the better choice.
Situational access also includes shared living arrangements. A couple or group of housemates may use the idea of splitting a major bill to reduce the pressure on the person whose account normally handles it. The trade-off is that shared responsibility can become unclear if everyone assumes someone else has checked the final status. I would assign one person to verify the complete payment and keep a simple shared note showing who contributed and when. The app can support the process, but it should not replace communication between the people involved.
Travel, temporary work, and changing schedules are other contexts where a smaller payment rhythm may feel useful. Yet these are also situations in which phone access, connectivity, and attention may be inconsistent. I would complete important setup before leaving home, keep the original bill details available, and avoid treating a split schedule as successful until I can see that the intended action has been recorded. That extra verification is particularly valuable when I am away from my usual bank branch, household, or support network.
Where the usual alternatives may be better
The most obvious alternative is a bank’s own bill-payment system. It may be preferable when I need a direct relationship with the account holding the money, a familiar record of transactions, or a process already recognized by a landlord or lender. A bank app can also be the safer choice when the payment recipient has strict instructions about how and when funds must arrive.
A budgeting app is better when the main question is not “how can I divide this bill?” but “can I afford all of my commitments this month?” Budgeting tools usually make it easier to compare rent or mortgage costs with groceries, utilities, subscriptions, and debt. Split Pay’s focused design may reduce distraction, but it also means I should not expect a full household financial overview from it.
Manual sinking funds are another realistic alternative. I can create a separate savings space, move a portion of money into it after each payday, and then make one conventional payment when the bill is due. This approach offers more control and may be easier to explain to a lender, but it requires discipline and does not provide the same dedicated focus. For someone who already manages money confidently, manual saving may be simpler. For someone who repeatedly forgets to reserve money, a purpose-built workflow can provide useful structure.
Remaining barriers and responsible use
The biggest barrier is not necessarily reading the screen; it is understanding the financial responsibility behind the split. A smaller installment can feel psychologically easier while the total obligation remains exactly the same. Users who are already short of money may be tempted to view the app as a solution to a deeper income problem. I would be careful here: if the full payment is not realistically covered by the planned schedule, dividing it does not remove the risk of falling behind.
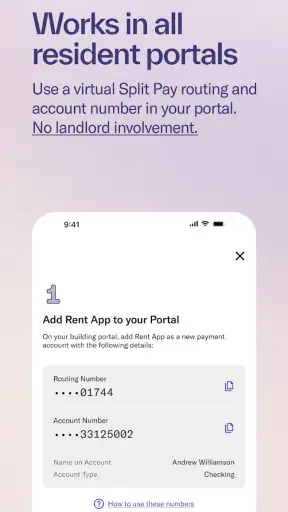
Another barrier is the need to verify compatibility with the recipient. Rent, mortgage, and vehicle payments are not interchangeable. A landlord may accept several payments, while a lender or finance company may expect a particular process. Before depending on the app, I would check the payment terms directly and keep enough time for a backup method. That is especially important for first-time use, holidays, weekends, or any month when income arrives later than usual.
There is also a human-access barrier. Some users may not want to manage an essential payment through a smartphone, while others may share a device or have limited private access to one. In those circumstances, a bank transfer, scheduled payment, or support from a trusted person may be more practical. I would not recommend moving an entire household payment routine into an app until everyone affected understands who is responsible for checking it.
Privacy deserves careful attention in any finance workflow. I would avoid entering information while using an unsecured public device, keep the phone protected, and review the final payment details before confirming. I would also maintain an independent record of due dates and amounts. That record is not redundant: it helps users with memory difficulties, protects against confusion between several recurring bills, and makes it easier to explain the arrangement to a partner or support person.
For users who need assistance, the best approach is collaborative rather than passive. A trusted helper can read the payment amount, confirm the intended date, or check that the user understands the next step, while the account holder remains involved in the decision. This supports independence without turning a sensitive financial task into something another person controls completely.
My inclusive verdict on Split Pay
After looking at the app through the needs of different users and situations, I see a clear strength: it concentrates on a real pressure point in personal finance. The free price makes it easy to consider, and the Everyone age rating keeps the presentation broadly approachable. Its strong 4.8 average and more than 100,000 installs indicate that the concept has found an audience, though I would still judge it by my own payment requirements rather than popularity alone.
I would recommend it to someone whose income arrives in several stages and who wants a dedicated way to organize rent, a mortgage, or a car payment. I would also recommend it to people who find large one-time obligations mentally overwhelming but can reliably reserve the necessary total over time. The focused approach may be less demanding than a full budgeting suite, and that can be a meaningful advantage for users dealing with attention, stress, or limited financial experience.
I would skip it as my primary solution if a lender or landlord requires one conventional payment, if I need detailed household budgeting, or if I cannot confidently cover the full obligation. In those cases, a bank tool, manual savings plan, or broader budgeting app may offer better control. I would also avoid using it without a backup calendar and a clear record, because accessibility includes being able to recover from confusion rather than hoping confusion never occurs.
My final view is positive but deliberately practical. Split Pay is most useful when it changes the timing of a manageable obligation, not when it disguises an unmanageable one. If you verify the recipient’s rules, check every amount, and keep an independent reminder, the app can make recurring housing or vehicle payments feel more compatible with real life. Its best quality is its focus; its main limitation is that focus cannot replace broader financial planning or personal responsibility.
Split Pay: Split Bills in Two FAQ
What is Split Pay: Split Bills in Two?
Split Pay: Split Bills in Two is designed to make shared expenses easier to manage when two people need to divide a bill. Instead of calculating each person’s portion manually, you can enter the bill information, choose how it should be split, and quickly see the amount each person owes. It can be useful for meals, household expenses, trips, subscriptions, and everyday payments between friends or partners.
How does Split Pay divide a bill between two people?
The app focuses on splitting expenses between two participants, making it suitable for simple one-to-one calculations. Depending on the available options, you can generally divide a total equally or assign different amounts or percentages when one person paid more than the other. Before confirming the result, carefully review the entered total, taxes, tips, and any custom adjustments to avoid an inaccurate calculation.
Can Split Pay handle tips, taxes, or unequal contributions?
Split Pay can be helpful when a bill is more complicated than a basic 50/50 division, particularly if you need to account for a tip, tax, discount, or unequal contribution. The exact tools may depend on the current version of the application and your device. It is best to check the calculated total against the original receipt, especially when several adjustments are involved.
Is Split Pay: Split Bills in Two free to download and use?
The availability of free features, advertising, and optional purchases can vary according to the platform and the version installed from the official app store. Before downloading, review the listing for current pricing information, subscription details, and any in-app purchase conditions. If the app offers premium tools, the basic bill-splitting function may still be available without payment, but this should be confirmed on your device.
Does Split Pay require an internet connection or access to my personal data?
A simple bill-splitting calculation may work without a continuous internet connection because the main task is performed directly on the device. However, internet access could be needed for downloading the app, displaying advertisements, updating content, or processing optional services. Check the permissions requested during installation and only grant access that seems necessary. Avoid entering sensitive financial information unless the app clearly explains how it is stored and protected.











